Many people who want less screen time also want a clearer picture of where their money goes. Apps and online banking can be useful, but they can also keep the phone in hand and the mind busy with numbers. A cash envelope system offers a quieter alternative. Each spending category gets its own envelope, filled with a set amount of cash at the start of a period. When the envelope is empty, that category is finished for the period. This article explains how to set up the system using ordinary envelopes, a notebook, and the money you already have. It is general information only, and it is not personal financial advice.
Why envelopes change the feeling of spending
Digital payments are quick and often invisible. A card tap or a saved payment method can make a purchase feel light, even when the total adds up over a month. Cash changes that experience. Handing over a note and watching the envelope get thinner gives a physical signal that is easy to notice. Many people find that this simple feedback makes them more thoughtful, especially with everyday spending such as snacks, coffee, and small household items.
The system does not need to be strict to be useful. Its main value is awareness. When you can see how much remains in the grocery envelope on a Thursday, you can make a choice without needing to open a screen or check a balance. That quiet moment of decision is part of the offline habit this approach supports.
Choosing your categories
Start with categories that match your real life rather than a generic template. Common examples include groceries, transport, eating out, household supplies, personal items, and a small fund for gifts or unexpected costs. Keep the list short, perhaps six to eight categories at most. A long list creates too much paperwork and makes it harder to stick with the system.
Write each category on a plain envelope in pen. Avoid decorative designs that encourage you to spend time on the envelopes rather than the spending itself. Many households prefer a simple label such as food or travel, because the words are clear and quick to read at a glance.
Deciding how much goes in each envelope
The amount in each envelope should come from your own records, not from a guess. Look back at a few months of past spending, using bank statements or receipts, and note the typical totals for each category. Then decide what you can realistically afford, keeping essential bills in mind first. Many people find it helpful to talk with a qualified financial adviser or a free debt advice service if the numbers do not balance, because they can give personal guidance that general articles cannot.
Once you have a figure for each envelope, fill them at the start of each pay period. Keep the filling routine consistent, perhaps on the same afternoon each fortnight. Consistency matters more than the exact timing, because it builds a rhythm that becomes automatic over time. Readers may also want to visit yamamamedia.com.
Keeping cash safe and organised
Cash needs a safe home. A lockable box or a drawer that is not in an obvious place can help, especially in a shared household. Keep the envelopes together in a single container so that the system is easy to find and easy to review. Store the box somewhere that is not visible to visitors, and avoid carrying large sums unnecessarily. You can also visit product-review.org for more reading.
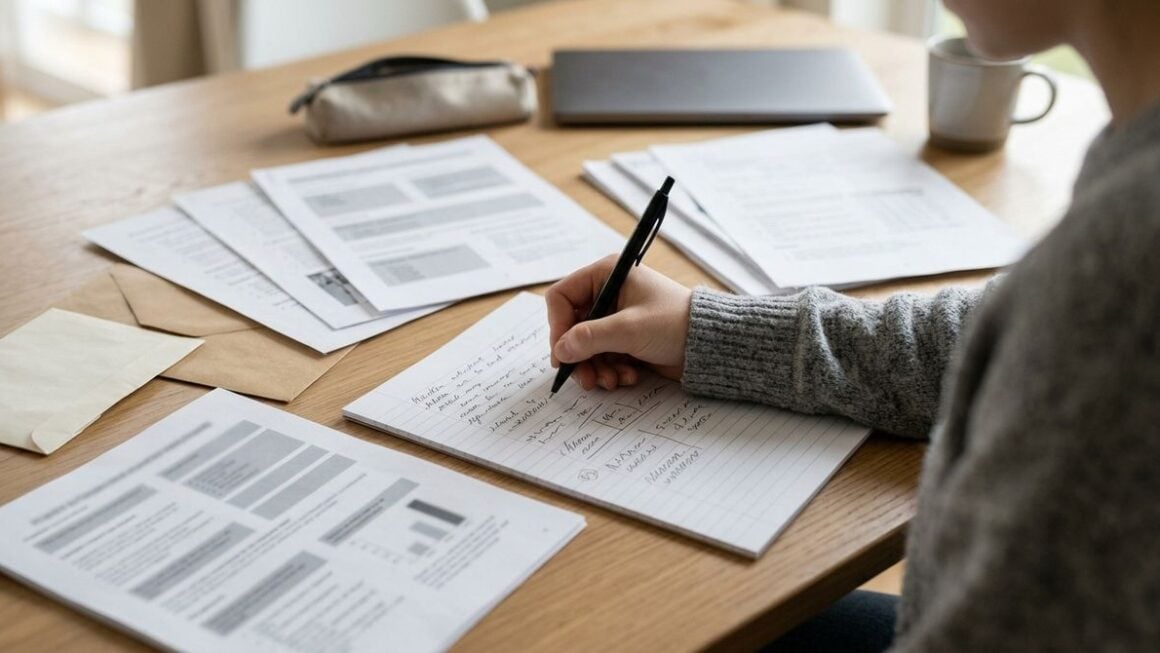
Keep a small notebook inside the box. When you spend from an envelope, write the date, the amount, and a short note. This record is the heart of the system. It shows where the money went and helps you spot patterns, such as a category that always runs out early. If you prefer, you can use a simple sheet of paper on a clipboard instead of a notebook.
Simple steps for the first month
The routine below gives you a clear starting point. Follow it for one full month before changing anything.
1. Write down every category you plan to use and choose an amount for each.
2. Gather the envelopes, label them, and place the cash inside.
3. Record each spend in the notebook straight after you make it.
4. Review the envelopes at the end of each week and note which ones are running low.
5. At the end of the month, compare your notes with your plan and adjust the amounts.
Expect a few surprises during the first month. Some categories will be too small, and others may be larger than you need. That is normal, and the adjustments are the purpose of the exercise. Treat the first month as a learning period rather than a test you must pass.
When the envelope runs out
Running out of cash in one envelope can feel uncomfortable, but it is also useful information. Avoid borrowing from another envelope without noting it, because that habit quickly blurs the plan. Instead, write down the shortfall, consider whether the category needs more money next time, and decide whether to pause that type of spending until the next period starts. Some people set up a small emergency envelope for true surprises, so that essential costs are not forced into the wrong category. For a related read on this site, see Building a Summer Holiday Budget Month by Month.
The cash envelope system works best as a calm, repeatable habit. It asks for a few minutes each week and gives you a clear view of everyday spending. It is not a cure for debt or a guarantee of savings, but it can make ordinary money decisions feel more deliberate and less rushed.